Have a restaurant, contractor, convenience store or other small business near the coast? It may be time to check Coterie again.
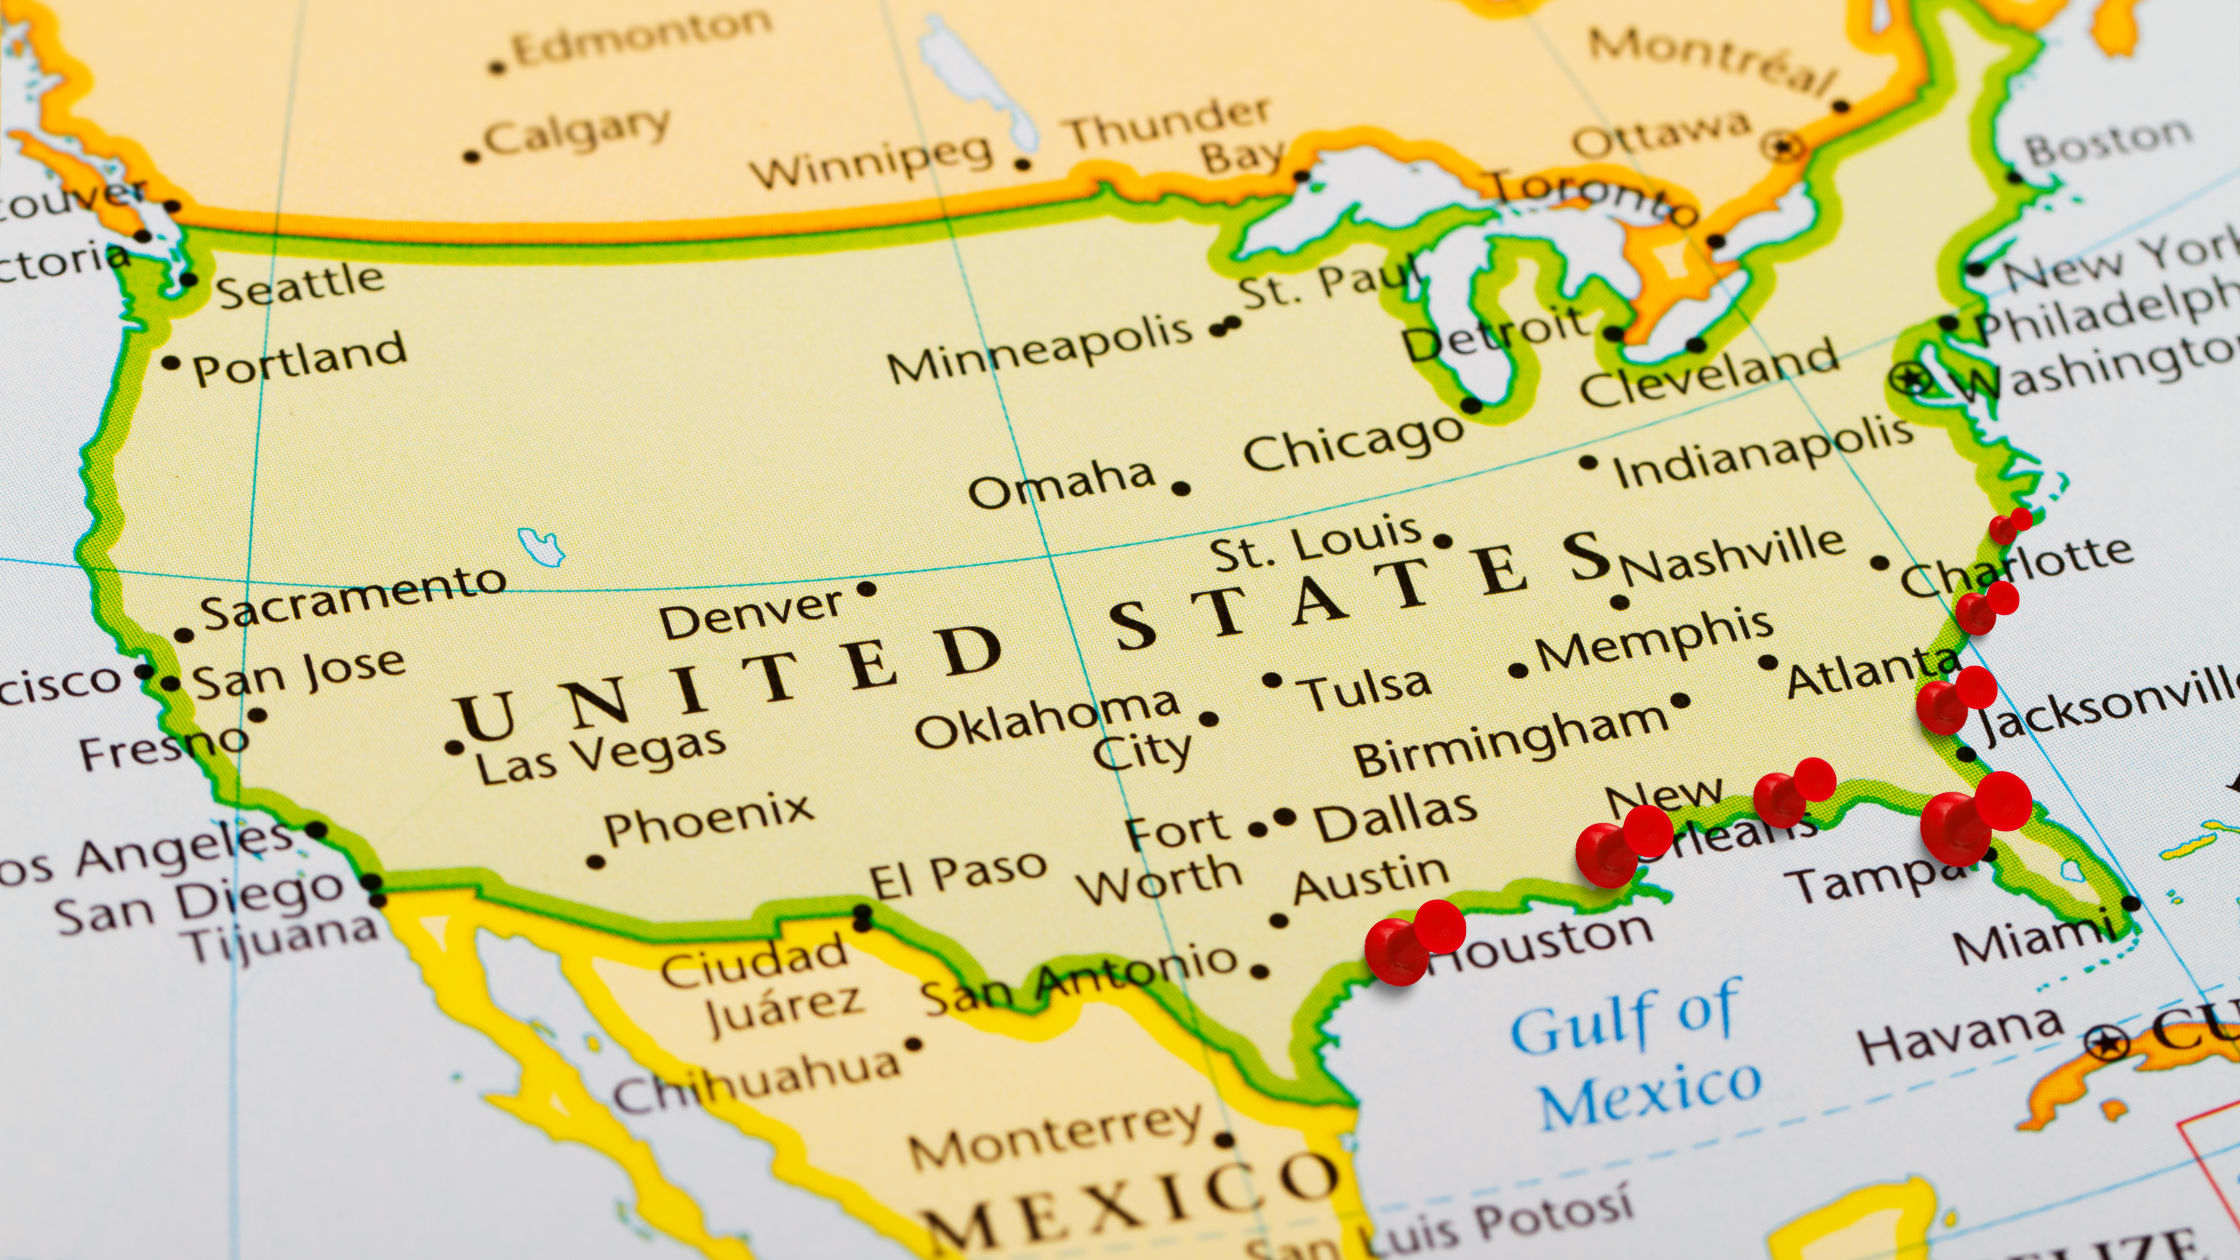
Coterie Insurance has expanded its Business Owners’ Policy (BOP) appetite for eligible small businesses located 3 to 26 miles from the coast across seven states:
For agents, that means more opportunities to quote coastal and coastal-adjacent small businesses that may not have fit Coterie’s appetite in the past.
There are also no additional industry restrictions specific to this coastal expansion. Restaurants, contractors, convenience stores and other businesses can be considered if they otherwise meet Coterie’s BOP appetite and underwriting requirements.
The biggest takeaway? Don’t assume a small business won’t fit based on what Coterie’s appetite used to be. Check Coterie first.
Coterie’s coastal BOP appetite at a glance
Coterie can now consider eligible small businesses located 3 to 26 miles from the coast in Florida, Texas, Mississippi, Alabama, Georgia, South Carolina and North Carolina.
Businesses located less than 3 miles from the coast remain ineligible under this coastal expansion.
Businesses more than 26 miles from the coast are considered inland and continue to follow applicable state-specific Coterie appetite and coverage requirements.
| State | Eligible Coastal Zone | Coastal BPP Limit | Building Coverage in Coastal Zone |
|---|---|---|---|
| Florida | 3–26 miles | Up to $250,000 | Not available* |
| Texas | 3–26 miles | Up to $250,000 | Not available |
| Mississippi | 3–26 miles | Up to $250,000 | Not available |
| Alabama | 3–26 miles | Up to $250,000 | Not available |
| Georgia | 3–26 miles | Up to $250,000 | Not available |
| South Carolina | 3–26 miles | Up to $250,000 | Not available |
| North Carolina | 3–26 miles | Up to $250,000 | Not available |
*Building coverage is unavailable statewide in Florida.
Eligible businesses remain subject to Coterie’s standard appetite, underwriting requirements and applicable state-specific coverage requirements.
Jump to coastal appetite by state
Looking for information about a specific state?
Florida | Texas | Mississippi | Alabama | Georgia | South Carolina | North Carolina
What changed with Coterie’s coastal business insurance appetite?
Coterie previously had broader coastal restrictions that prevented many small businesses located within approximately 26 miles of the coast from being eligible for a BOP.
Our expanded coastal appetite opens more of that area for eligible small businesses.
Here’s the simplest way to think about coastal eligibility:
Less than 3 miles from the coast: Not eligible under Coterie’s coastal BOP expansion.
3–26 miles from the coast: Eligible businesses can now be considered under Coterie’s coastal appetite and applicable coverage requirements.
More than 26 miles from the coast: Standard state-specific Coterie appetite and coverage requirements apply.
And agents don’t need to determine exact coastal eligibility on their own before considering Coterie. Check our current appetite and start a quote to see whether a specific risk fits.
Florida coastal business insurance appetite
Coterie can consider eligible Florida small businesses located 3 to 26 miles from the coast for a BOP.
Florida was the first state included in Coterie’s expanded coastal appetite and has some coverage requirements that apply statewide.
Florida coastal appetite details
| Requirement | Florida |
|---|---|
| Eligible coastal distance | 3–26 miles |
| Less than 3 miles | Ineligible |
| Business Personal Property (BPP) | Up to $250,000 in coastal zone |
| Building coverage | Not available statewide |
| Business Income | $10,000 |
| Property Claims deductible | $2,500 in coastal zone |
| Wind/Hail deductible | 5% |
| Additional coastal industry restrictions | None |
Businesses more than 26 miles from the Florida coast continue to follow applicable inland Florida requirements.
Texas coastal business insurance appetite
Coterie can consider eligible Texas small businesses located 3 to 26 miles from the coast for a BOP.
Texas coastal appetite details
| Requirement | Texas |
|---|---|
| Eligible coastal distance | 3–26 miles |
| Less than 3 miles | Ineligible |
| Business Personal Property (BPP) | Up to $250,000 |
| Building coverage | Not available in coastal zone |
| Business Income | $10,000 |
| Property Claims deductible | $2,500 |
| Wind/Hail deductible | 5%, subject to a $2,500 minimum |
| Additional coastal industry restrictions | None |
Eligible Texas coastal risks are written with Spinnaker Insurance Company. Inland Texas risks continue to follow Coterie’s existing carrier placement and state-specific coverage rules.
Mississippi coastal business insurance appetite
Coterie can consider eligible Mississippi small businesses located 3 to 26 miles from the coast for a BOP.
Mississippi coastal appetite details
| Requirement | Mississippi |
|---|---|
| Eligible coastal distance | 3–26 miles |
| Less than 3 miles | Ineligible |
| Business Personal Property (BPP) | Up to $250,000 |
| Building coverage | Not available in coastal zone |
| Business Income | $10,000 |
| Property Claims deductible | $2,500 |
| Wind/Hail deductible | 5%, subject to a $2,500 minimum |
| Additional coastal industry restrictions | None |
Businesses more than 26 miles from the coast continue to follow applicable inland Mississippi appetite and coverage requirements.
Alabama coastal business insurance appetite
Coterie can consider eligible Alabama small businesses located 3 to 26 miles from the coast for a BOP.
Alabama coastal appetite details
| Requirement | Alabama |
|---|---|
| Eligible coastal distance | 3–26 miles |
| Less than 3 miles | Ineligible |
| Business Personal Property (BPP) | Up to $250,000 |
| Building coverage | Not available in coastal zone |
| Business Income | $10,000 |
| Property Claims deductible | $2,500 |
| Wind/Hail deductible | 5%, subject to a $2,500 minimum |
| Additional coastal industry restrictions | None |
Businesses more than 26 miles from the coast continue to follow applicable inland Alabama appetite and coverage requirements.
Georgia coastal business insurance appetite
Coterie can consider eligible Georgia small businesses located 3 to 26 miles from the coast for a BOP.
Georgia coastal appetite details
| Requirement | Georgia |
|---|---|
| Eligible coastal distance | 3–26 miles |
| Less than 3 miles | Ineligible |
| Business Personal Property (BPP) | Up to $250,000 |
| Building coverage | Not available in coastal zone |
| Business Income | $10,000 |
| Property Claims deductible | $2,500 |
| Wind/Hail deductible | 5%, subject to a $2,500 minimum |
| Additional coastal industry restrictions | None |
Businesses more than 26 miles from the coast continue to follow applicable inland Georgia appetite and coverage requirements.
South Carolina coastal business insurance appetite
Coterie can consider eligible South Carolina small businesses located 3 to 26 miles from the coast for a BOP.
South Carolina coastal appetite details
| Requirement | South Carolina |
|---|---|
| Eligible coastal distance | 3–26 miles |
| Less than 3 miles | Ineligible |
| Business Personal Property (BPP) | Up to $250,000 |
| Building coverage | Not available in coastal zone |
| Business Income | $10,000 |
| Property Claims deductible | $2,500 |
| Wind/Hail deductible | 5%, subject to a $2,500 minimum |
| Additional coastal industry restrictions | None |
South Carolina uses a state-specific Wind/Hail endorsement for eligible coastal risks. Businesses more than 26 miles from the coast continue to follow applicable inland South Carolina appetite and coverage requirements.
North Carolina coastal business insurance appetite
Coterie can consider eligible North Carolina small businesses located 3 to 26 miles from the coast for a BOP.
North Carolina coastal appetite details
| Requirement | North Carolina |
|---|---|
| Eligible coastal distance | 3–26 miles |
| Less than 3 miles | Ineligible |
| Business Personal Property (BPP) | Up to $250,000 |
| Building coverage | Not available in coastal zone |
| Business Income | $10,000 |
| Property Claims deductible | $2,500 |
| Wind/Hail deductible | 5%, subject to a $2,500 minimum |
| Additional coastal industry restrictions | None |
Businesses more than 26 miles from the coast continue to follow applicable inland North Carolina appetite and coverage requirements.
What types of coastal businesses does Coterie want to write?
This is one of the most important parts of Coterie’s coastal expansion.
There are no additional industry restrictions specific to the expanded coastal appetite.
That means agents shouldn’t think of this as a short list of newly eligible coastal industries. If a small business otherwise fits Coterie’s BOP appetite and underwriting requirements, its industry isn’t automatically excluded simply because the business is located within the newly opened coastal zone.
Opportunities can include businesses such as:
- Restaurants and food-service businesses
- Contractors and trades
- Convenience stores
- Retail businesses
- Professional and office-based businesses
- Personal-service businesses
- Other eligible small businesses within Coterie’s appetite
This is especially important for industries such as restaurants, contractors and convenience stores that agents may have previously associated with coastal restrictions.
If you passed on one of these businesses because of its coastal location, check it again.
What property coverage is available for businesses near the coast?
For eligible businesses within the 3–26 mile coastal zone, Coterie can offer up to $250,000 in Business Personal Property coverage.
Building coverage is not available for risks in the coastal zone. Eligible coastal property risks therefore need to be written with Business Personal Property rather than Building coverage.
For Texas, Mississippi, Alabama, Georgia, South Carolina and North Carolina, eligible coastal quotes also include:
- $10,000 in Business Income coverage
- A $2,500 Property Claims deductible
- A 5% Wind/Hail deductible, subject to a $2,500 minimum
Florida follows its applicable Florida coastal and statewide coverage requirements as outlined above.
Why should agents check Coterie first?
Small commercial appetite changes.
A business that didn’t fit an insurance provider’s appetite in the past may fit today. Coterie’s coastal expansion is a perfect example.
That’s why agents shouldn’t have to memorize every eligibility rule, distance requirement or coverage threshold before considering Coterie.
Instead, get in the habit of checking Coterie first.
Have a restaurant? Check Coterie.
Working with a contractor? Check Coterie.
Quoting a convenience store? Check Coterie.
Have a small business near the coast that you previously assumed wouldn’t fit? Check Coterie again.
Coterie’s appetite covers a broad range of small business industries. Checking our current appetite can help you uncover opportunities you might otherwise overlook.
What does Coterie look for in small business insurance?
Coterie focuses on small commercial businesses across a broad range of industries.
Our goal is to make it easier for independent insurance agents to place small business coverage without unnecessarily limiting themselves to a handful of familiar industries.
That can mean restaurants and retailers on Main Street, contractors working throughout the community, professional-service businesses, convenience stores and many other types of small businesses.
Every risk still needs to meet Coterie’s current product appetite, eligibility and underwriting requirements. But agents shouldn’t rule out an opportunity based only on what they remember our appetite being in the past.
Check current appetite first.
That is particularly important as Coterie continues to evolve and expand the businesses we can consider.
Have a previously declined coastal opportunity? Check again.
New leads aren’t the only opportunity created by an appetite expansion.
Think about the businesses already in your pipeline or book.
If you have prospects or customers in Florida, Texas, Mississippi, Alabama, Georgia, South Carolina or North Carolina that you previously didn’t bring to Coterie because of their proximity to the coast, now is a good time to revisit them.
Pay particular attention to businesses located approximately 3 to 26 miles from the coastline, including restaurants, contractors, convenience stores and other small businesses that fit Coterie’s appetite.
An opportunity that didn’t fit before may fit today.
Frequently asked questions about Coterie’s coastal appetite
Does Coterie Insurance write businesses near the coast?
Yes. Coterie can consider eligible small businesses located 3 to 26 miles from the coast for a Business Owners’ Policy in Florida, Texas, Mississippi, Alabama, Georgia, South Carolina and North Carolina. Businesses less than 3 miles from the coast remain ineligible under this coastal expansion.
Which states are included in Coterie’s coastal BOP appetite?
Coterie’s coastal BOP appetite includes Florida, Texas, Mississippi, Alabama, Georgia, South Carolina and North Carolina.
How close to the coast can a business be and still qualify for a Coterie BOP?
Eligible businesses located at least 3 miles and up to 26 miles from the coast can be considered under Coterie’s coastal BOP appetite in the participating states. Locations less than 3 miles from the coast remain ineligible under this expansion.
Does Coterie write coastal businesses in Florida?
Yes. Eligible Florida small businesses located 3 to 26 miles from the coast can be considered for a Coterie BOP, subject to applicable Florida appetite, coverage and underwriting requirements.
Does Coterie write coastal businesses in Texas?
Yes. Eligible Texas small businesses located 3 to 26 miles from the coast can be considered for a Coterie BOP. Eligible coastal Texas risks are written with Spinnaker Insurance Company.
Can Coterie insure restaurants near the coast?
Restaurants located within the eligible coastal zone can be considered if they otherwise meet Coterie’s BOP appetite and underwriting requirements. There are no additional industry restrictions specific to the coastal expansion.
Can Coterie insure contractors near the coast?
Eligible contractors located within the 3–26 mile coastal zone can be considered if they otherwise meet Coterie’s BOP appetite and underwriting requirements.
Can Coterie insure convenience stores near the coast?
Eligible convenience stores can be considered within Coterie’s expanded coastal BOP appetite if they meet Coterie’s standard appetite and underwriting requirements.
Are any industries specifically excluded from Coterie’s coastal expansion?
There are no additional industry restrictions specific to Coterie’s coastal expansion. Businesses must still meet Coterie’s standard BOP appetite, eligibility and underwriting requirements.
Does Coterie offer Building coverage for coastal businesses?
Building coverage is not available for risks within the 3–26 mile coastal zone. In Florida, Building coverage is unavailable statewide.
How much Business Personal Property coverage is available for coastal businesses?
Coterie can offer up to $250,000 in Business Personal Property coverage for eligible businesses within the 3–26 mile coastal zone.
What happens if a business is more than 26 miles from the coast?
Businesses more than 26 miles from the coast are considered inland for this coastal initiative and continue to follow Coterie’s applicable state-specific appetite and coverage requirements.
What happens if a business is less than 3 miles from the coast?
Businesses located less than 3 miles from the coast remain ineligible for a BOP under Coterie’s coastal expansion.
How can an agent determine if a business fits Coterie’s appetite?
Check Coterie’s current appetite and start a quote in Dashboard. Eligibility depends on the individual business, location, requested coverage and applicable underwriting requirements.
Have a small business opportunity? Check Coterie first.
Coterie’s expanded coastal appetite gives independent agents more opportunities to help protect small businesses across Florida, Texas, Mississippi, Alabama, Georgia, South Carolina and North Carolina.
But coastal business is only part of the opportunity.
Appetite evolves, and an old assumption shouldn’t keep a good small business opportunity from being considered.
Whether you’re working with a restaurant, contractor, convenience store or another small business, make checking Coterie part of your process.
Have a small business to place? Check Coterie first.